Skip to content

Automated mortgage quality control

QC findings you can defend.

Flightline reviews the whole loan file, follows the evidence when something doesn’t add up, and returns defensible findings the same day.

Programs we test against

  • Fannie Mae
  • Freddie Mac
  • FHA
  • VA
  • Ginnie Mae
  • USDA
  • Non-QM

Loan file in.QC report out.

Send the whole file as you have it. No document mapping, re-keying or prep. Flightline reviews it as one loan and typically returns the QC report within the hour.

How a Flightline finding is made

Loan 2026-0231 · an illustrative purchase

The file looks ready.The balance clears.

Asset review compares the ending balance on the statement with the funds the loan needs: $34,091.29 against $33,500.00. On the printed figures, this purchase is ready to close. The statement’s own transactions say otherwise.

Funds to close and reservesVerifiedNot supported$31,391.29 < $33,500.00 required
Checking account statement · June 1–30Pages 1–3
DateTransactionAmountRecomputed
06/01Opening balance—$18,402.16
06/03Payroll deposit+$4,118.40$22,520.56
06/07Transfer to savings−$1,500.00$21,020.56
06/12Mortgage payment−$2,284.55$18,736.01
06/15Sample Auto Finance−$412.00$18,324.01
06/17Payroll deposit+$4,118.40$22,442.41
06/21Card payment−$551.12$21,891.29
06/28Deposit+$9,500.00$31,391.29
Ending balance, as printed
$34,091.29
Ending balance, from its own transactions
$31,391.29
Difference
$2,700.00

Illustrative file. Names, pages and amounts are fictional.

Before raising a findingAssets · Funds to close

Could anything in the file explain $2,700.00?

  1. Recompute the balance from its transactions $31,391.29, not the $34,091.29 printed
  2. A missing page?Ruled out. All three pages are present and carry forward
  3. A pending item?Ruled out. None on the statement matches $2,700.00
  4. A transfer between own accounts?Ruled out. Savings shows no $2,700.00
  5. Against the funds the loan needs $2,108.71 short of $33,500.00
Open findingAssets · Funds to close

Verified funds are not supported. The statement does not foot to its own transactions.

Shortfall against required funds$2,108.71
Other explanations tested against the file
  • A missing page: all three pages are present and carry forward.
  • A pending item: none on the statement matches $2,700.00.
  • A transfer between own accounts: savings shows no $2,700.00.

RequirementFannie Mae Selling Guide B3-4.2-01, Verification of Deposits and Assets

Cited as in effect on the review date.

Open findingCredit

A $412.00 monthly payment is not on the application.

Checking statement, June · page 2
06/15 Sample Auto Finance−$412.00
Checking statement, May · page 2
05/15 Sample Auto Finance−$412.00
Application · Liabilities
This creditorNot listed

RequirementFannie Mae Selling Guide B3‑6-05

Open findingAppraisal

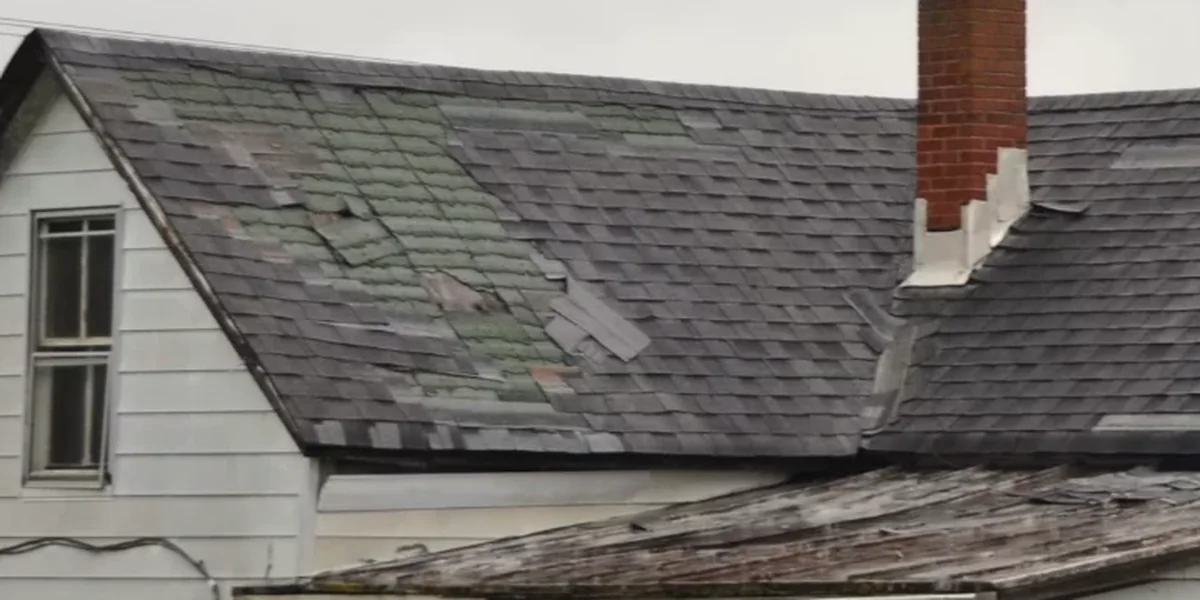
The photos show a patched roof the C3 rating and ‘no repairs’ do not address.

Appraisal addendum, rear view: a patched section of mismatched shingles, with tabs lifting, across the main roof
Photo addendum · page 14 · Rear view

RequirementFannie Mae Selling Guide B4‑1.3‑06

Open findingCompliance

Closing Disclosure received less than three business days before consummation.

  1. Wed 26Received
  2. Thu 27Day 1
  3. Fri 28Closed
  4. Sat 29Earliest

Requirement12 CFR 1026.19(f)(1)(ii)

Resolved in fileAssets

The $9,500.00 deposit is the borrower’s own savings.

Savings statement · page 1
06/28 Transfer to checking−$9,500.00

No exception raised.

RequirementFannie Mae Selling Guide B3‑4.2‑02

Appraisal
Income
Program eligibility
Compliance
Assets
Fraud signals
Credit
Closing
AUS reconciliation
Undisclosed debt
Fair lending
Loan officer compliance
Passed Finding Resolved in file The statement above

Illustrative. Each square is one test; which tests apply depends on the loan.

What the file saysOccupancy · a refinance

The borrower will live here.

  1. ApplicationPrimary residence
  2. Homeowner’s insuranceA landlord policy
  3. Tax return$31,000 of rental income from the property

The evidence doesn’t support the file’s occupancy story.

It doesn’t stopat the first answer.

Recomputed from its own transactions, the statement is $2,700.00 short of what it prints. Before calling that a finding, Flightline looks for anything in the file that would explain it, and raises it only when nothing does.

Funds to close and reservesVerifiedNot supported$31,391.29 < $33,500.00 required
Checking account statement · June 1–30Pages 1–3
DateTransactionAmountRecomputed
06/01Opening balance—$18,402.16
06/03Payroll deposit+$4,118.40$22,520.56
06/07Transfer to savings−$1,500.00$21,020.56
06/12Mortgage payment−$2,284.55$18,736.01
06/15Sample Auto Finance−$412.00$18,324.01
06/17Payroll deposit+$4,118.40$22,442.41
06/21Card payment−$551.12$21,891.29
06/28Deposit+$9,500.00$31,391.29
Ending balance, as printed
$34,091.29
Ending balance, from its own transactions
$31,391.29
Difference
$2,700.00

Illustrative file. Names, pages and amounts are fictional.

Before raising a findingAssets · Funds to close

Could anything in the file explain $2,700.00?

  1. Recompute the balance from its transactions $31,391.29, not the $34,091.29 printed
  2. A missing page?Ruled out. All three pages are present and carry forward
  3. A pending item?Ruled out. None on the statement matches $2,700.00
  4. A transfer between own accounts?Ruled out. Savings shows no $2,700.00
  5. Against the funds the loan needs $2,108.71 short of $33,500.00
Open findingAssets · Funds to close

Verified funds are not supported. The statement does not foot to its own transactions.

Shortfall against required funds$2,108.71
Other explanations tested against the file
  • A missing page: all three pages are present and carry forward.
  • A pending item: none on the statement matches $2,700.00.
  • A transfer between own accounts: savings shows no $2,700.00.

RequirementFannie Mae Selling Guide B3-4.2-01, Verification of Deposits and Assets

Cited as in effect on the review date.

Open findingCredit

A $412.00 monthly payment is not on the application.

Checking statement, June · page 2
06/15 Sample Auto Finance−$412.00
Checking statement, May · page 2
05/15 Sample Auto Finance−$412.00
Application · Liabilities
This creditorNot listed

RequirementFannie Mae Selling Guide B3‑6-05

Open findingAppraisal

The photos show a patched roof the C3 rating and ‘no repairs’ do not address.

Appraisal addendum, rear view: a patched section of mismatched shingles, with tabs lifting, across the main roof
Photo addendum · page 14 · Rear view

RequirementFannie Mae Selling Guide B4‑1.3‑06

Open findingCompliance

Closing Disclosure received less than three business days before consummation.

  1. Wed 26Received
  2. Thu 27Day 1
  3. Fri 28Closed
  4. Sat 29Earliest

Requirement12 CFR 1026.19(f)(1)(ii)

Resolved in fileAssets

The $9,500.00 deposit is the borrower’s own savings.

Savings statement · page 1
06/28 Transfer to checking−$9,500.00

No exception raised.

RequirementFannie Mae Selling Guide B3‑4.2‑02

Appraisal
Income
Program eligibility
Compliance
Assets
Fraud signals
Credit
Closing
AUS reconciliation
Undisclosed debt
Fair lending
Loan officer compliance
Passed Finding Resolved in file The statement above

Illustrative. Each square is one test; which tests apply depends on the loan.

What the file saysOccupancy · a refinance

The borrower will live here.

  1. ApplicationPrimary residence
  2. Homeowner’s insuranceA landlord policy
  3. Tax return$31,000 of rental income from the property

The evidence doesn’t support the file’s occupancy story.

Across the file.Every kind of evidence.

Documents read against each other, photos checked against the report, disclosures timed, and what the file already answers left unraised.

Funds to close and reservesVerifiedNot supported$31,391.29 < $33,500.00 required
Checking account statement · June 1–30Pages 1–3
DateTransactionAmountRecomputed
06/01Opening balance—$18,402.16
06/03Payroll deposit+$4,118.40$22,520.56
06/07Transfer to savings−$1,500.00$21,020.56
06/12Mortgage payment−$2,284.55$18,736.01
06/15Sample Auto Finance−$412.00$18,324.01
06/17Payroll deposit+$4,118.40$22,442.41
06/21Card payment−$551.12$21,891.29
06/28Deposit+$9,500.00$31,391.29
Ending balance, as printed
$34,091.29
Ending balance, from its own transactions
$31,391.29
Difference
$2,700.00

Illustrative file. Names, pages and amounts are fictional.

Before raising a findingAssets · Funds to close

Could anything in the file explain $2,700.00?

  1. Recompute the balance from its transactions $31,391.29, not the $34,091.29 printed
  2. A missing page?Ruled out. All three pages are present and carry forward
  3. A pending item?Ruled out. None on the statement matches $2,700.00
  4. A transfer between own accounts?Ruled out. Savings shows no $2,700.00
  5. Against the funds the loan needs $2,108.71 short of $33,500.00
Open findingAssets · Funds to close

Verified funds are not supported. The statement does not foot to its own transactions.

Shortfall against required funds$2,108.71
Other explanations tested against the file
  • A missing page: all three pages are present and carry forward.
  • A pending item: none on the statement matches $2,700.00.
  • A transfer between own accounts: savings shows no $2,700.00.

RequirementFannie Mae Selling Guide B3-4.2-01, Verification of Deposits and Assets

Cited as in effect on the review date.

Open findingCredit

A $412.00 monthly payment is not on the application.

Checking statement, June · page 2
06/15 Sample Auto Finance−$412.00
Checking statement, May · page 2
05/15 Sample Auto Finance−$412.00
Application · Liabilities
This creditorNot listed

RequirementFannie Mae Selling Guide B3‑6-05

Open findingAppraisal

The photos show a patched roof the C3 rating and ‘no repairs’ do not address.

Appraisal addendum, rear view: a patched section of mismatched shingles, with tabs lifting, across the main roof
Photo addendum · page 14 · Rear view

RequirementFannie Mae Selling Guide B4‑1.3‑06

Open findingCompliance

Closing Disclosure received less than three business days before consummation.

  1. Wed 26Received
  2. Thu 27Day 1
  3. Fri 28Closed
  4. Sat 29Earliest

Requirement12 CFR 1026.19(f)(1)(ii)

Resolved in fileAssets

The $9,500.00 deposit is the borrower’s own savings.

Savings statement · page 1
06/28 Transfer to checking−$9,500.00

No exception raised.

RequirementFannie Mae Selling Guide B3‑4.2‑02

Appraisal
Income
Program eligibility
Compliance
Assets
Fraud signals
Credit
Closing
AUS reconciliation
Undisclosed debt
Fair lending
Loan officer compliance
Passed Finding Resolved in file The statement above

Illustrative. Each square is one test; which tests apply depends on the loan.

What the file saysOccupancy · a refinance

The borrower will live here.

  1. ApplicationPrimary residence
  2. Homeowner’s insuranceA landlord policy
  3. Tax return$31,000 of rental income from the property

The evidence doesn’t support the file’s occupancy story.

Hundreds of tests,at once.

Each runs on the file it applies to, at the same depth as the one above.

Funds to close and reservesVerifiedNot supported$31,391.29 < $33,500.00 required
Checking account statement · June 1–30Pages 1–3
DateTransactionAmountRecomputed
06/01Opening balance—$18,402.16
06/03Payroll deposit+$4,118.40$22,520.56
06/07Transfer to savings−$1,500.00$21,020.56
06/12Mortgage payment−$2,284.55$18,736.01
06/15Sample Auto Finance−$412.00$18,324.01
06/17Payroll deposit+$4,118.40$22,442.41
06/21Card payment−$551.12$21,891.29
06/28Deposit+$9,500.00$31,391.29
Ending balance, as printed
$34,091.29
Ending balance, from its own transactions
$31,391.29
Difference
$2,700.00

Illustrative file. Names, pages and amounts are fictional.

Before raising a findingAssets · Funds to close

Could anything in the file explain $2,700.00?

  1. Recompute the balance from its transactions $31,391.29, not the $34,091.29 printed
  2. A missing page?Ruled out. All three pages are present and carry forward
  3. A pending item?Ruled out. None on the statement matches $2,700.00
  4. A transfer between own accounts?Ruled out. Savings shows no $2,700.00
  5. Against the funds the loan needs $2,108.71 short of $33,500.00
Open findingAssets · Funds to close

Verified funds are not supported. The statement does not foot to its own transactions.

Shortfall against required funds$2,108.71
Other explanations tested against the file
  • A missing page: all three pages are present and carry forward.
  • A pending item: none on the statement matches $2,700.00.
  • A transfer between own accounts: savings shows no $2,700.00.

RequirementFannie Mae Selling Guide B3-4.2-01, Verification of Deposits and Assets

Cited as in effect on the review date.

Open findingCredit

A $412.00 monthly payment is not on the application.

Checking statement, June · page 2
06/15 Sample Auto Finance−$412.00
Checking statement, May · page 2
05/15 Sample Auto Finance−$412.00
Application · Liabilities
This creditorNot listed

RequirementFannie Mae Selling Guide B3‑6-05

Open findingAppraisal

The photos show a patched roof the C3 rating and ‘no repairs’ do not address.

Appraisal addendum, rear view: a patched section of mismatched shingles, with tabs lifting, across the main roof
Photo addendum · page 14 · Rear view

RequirementFannie Mae Selling Guide B4‑1.3‑06

Open findingCompliance

Closing Disclosure received less than three business days before consummation.

  1. Wed 26Received
  2. Thu 27Day 1
  3. Fri 28Closed
  4. Sat 29Earliest

Requirement12 CFR 1026.19(f)(1)(ii)

Resolved in fileAssets

The $9,500.00 deposit is the borrower’s own savings.

Savings statement · page 1
06/28 Transfer to checking−$9,500.00

No exception raised.

RequirementFannie Mae Selling Guide B3‑4.2‑02

Appraisal
Income
Program eligibility
Compliance
Assets
Fraud signals
Credit
Closing
AUS reconciliation
Undisclosed debt
Fair lending
Loan officer compliance
Passed Finding Resolved in file The statement above

Illustrative. Each square is one test; which tests apply depends on the loan.

What the file saysOccupancy · a refinance

The borrower will live here.

  1. ApplicationPrimary residence
  2. Homeowner’s insuranceA landlord policy
  3. Tax return$31,000 of rental income from the property

The evidence doesn’t support the file’s occupancy story.

Tests answer the questions you know to ask.The review finds what doesn’t fit.

Flightline builds the story of the loan, then follows anything that doesn’t fit, across every document in the file.

Funds to close and reservesVerifiedNot supported$31,391.29 < $33,500.00 required
Checking account statement · June 1–30Pages 1–3
DateTransactionAmountRecomputed
06/01Opening balance—$18,402.16
06/03Payroll deposit+$4,118.40$22,520.56
06/07Transfer to savings−$1,500.00$21,020.56
06/12Mortgage payment−$2,284.55$18,736.01
06/15Sample Auto Finance−$412.00$18,324.01
06/17Payroll deposit+$4,118.40$22,442.41
06/21Card payment−$551.12$21,891.29
06/28Deposit+$9,500.00$31,391.29
Ending balance, as printed
$34,091.29
Ending balance, from its own transactions
$31,391.29
Difference
$2,700.00

Illustrative file. Names, pages and amounts are fictional.

Before raising a findingAssets · Funds to close

Could anything in the file explain $2,700.00?

  1. Recompute the balance from its transactions $31,391.29, not the $34,091.29 printed
  2. A missing page?Ruled out. All three pages are present and carry forward
  3. A pending item?Ruled out. None on the statement matches $2,700.00
  4. A transfer between own accounts?Ruled out. Savings shows no $2,700.00
  5. Against the funds the loan needs $2,108.71 short of $33,500.00
Open findingAssets · Funds to close

Verified funds are not supported. The statement does not foot to its own transactions.

Shortfall against required funds$2,108.71
Other explanations tested against the file
  • A missing page: all three pages are present and carry forward.
  • A pending item: none on the statement matches $2,700.00.
  • A transfer between own accounts: savings shows no $2,700.00.

RequirementFannie Mae Selling Guide B3-4.2-01, Verification of Deposits and Assets

Cited as in effect on the review date.

Open findingCredit

A $412.00 monthly payment is not on the application.

Checking statement, June · page 2
06/15 Sample Auto Finance−$412.00
Checking statement, May · page 2
05/15 Sample Auto Finance−$412.00
Application · Liabilities
This creditorNot listed

RequirementFannie Mae Selling Guide B3‑6-05

Open findingAppraisal

The photos show a patched roof the C3 rating and ‘no repairs’ do not address.

Appraisal addendum, rear view: a patched section of mismatched shingles, with tabs lifting, across the main roof
Photo addendum · page 14 · Rear view

RequirementFannie Mae Selling Guide B4‑1.3‑06

Open findingCompliance

Closing Disclosure received less than three business days before consummation.

  1. Wed 26Received
  2. Thu 27Day 1
  3. Fri 28Closed
  4. Sat 29Earliest

Requirement12 CFR 1026.19(f)(1)(ii)

Resolved in fileAssets

The $9,500.00 deposit is the borrower’s own savings.

Savings statement · page 1
06/28 Transfer to checking−$9,500.00

No exception raised.

RequirementFannie Mae Selling Guide B3‑4.2‑02

Appraisal
Income
Program eligibility
Compliance
Assets
Fraud signals
Credit
Closing
AUS reconciliation
Undisclosed debt
Fair lending
Loan officer compliance
Passed Finding Resolved in file The statement above

Illustrative. Each square is one test; which tests apply depends on the loan.

What the file saysOccupancy · a refinance

The borrower will live here.

  1. ApplicationPrimary residence
  2. Homeowner’s insuranceA landlord policy
  3. Tax return$31,000 of rental income from the property

The evidence doesn’t support the file’s occupancy story.

Faster. Broader. Deeper.

QC has always forced a tradeoff between coverage, depth and turnaround time. Flightline removes it.

  • FasterA full-file review typically comes back within the hour.
  • BroaderHundreds of tests run on every file they apply to.
  • DeeperFlightline follows evidence across the file and verifies its conclusions before raising a finding.

QC capacity that scales with volume, not headcount.

Where capital is at risk, the finding has to hold.Two control points. One standard.

Prefunding, a finding stops a defect before the lender commits capital to it. Post-closing, it is the last chance to find a defect before an investor, an insurer or an auditor does.

Run Flightline at either control point, or both. Wherever you run it, the findings are held to the same requirements, with the same evidence behind each one.

  1. Application
  2. Underwriting
  3. Prefunding QCBefore capital is committed
  4. Closing and funding
  5. Post-closing QCBefore an investor, insurer or auditor finds it
  6. Sale and delivery
  7. Servicing

From one findingto the board report.

The same evidence feeds everything a QC program owes the business: the loan audit report, the monthly report to management, and the corrective action that follows.

Loan audit report

Every finding with its evidence, requirement, effect on the loan and the lender’s response, sealed when it is issued.

Monthly QC report

Findings by program, channel, region and review area, trended month over month for management.

Corrective action plan

Repeat findings become a plan: root cause, owner, deadline, and the follow-up review that shows it worked.

Illustrative figures.

See how the platform works

Send us a fileyou’ve already closed.

The fastest way to judge Flightline is on a loan your team already knows. We’ll show you what it finds, and you decide whether it holds.

  • The issues it finds, and whether they hold
  • The exceptions it correctly does not raise
  • The work left for your reviewer